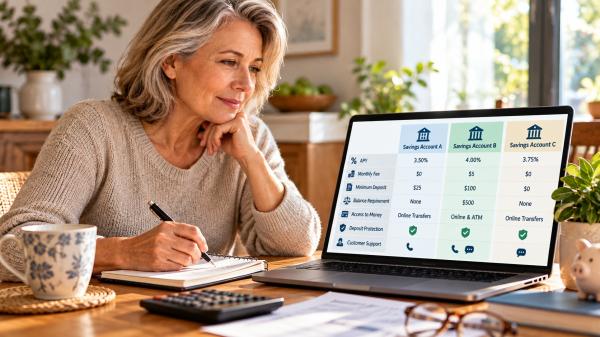
A high-yield savings account can help your money earn interest while remaining accessible for future expenses. However, comparing accounts involves more than choosing the one with the highest advertised rate. Fees, minimum balance requirements, deposit insurance, and transfer options can all affect your experience.
The best way to compare high-yield savings accounts is to evaluate their annual percentage yield (APY), costs, account requirements, and accessibility side by side. Understanding these differences can help you identify an account that fits your savings goals and banking preferences.
Start by Comparing APY
Annual percentage yield, or APY, measures how much interest an account earns over one year, including the effect of compounding. It provides a useful basis for comparing savings accounts.
A higher APY generally means more interest earned on the same balance, assuming the rate remains unchanged and other conditions are equal.
For example, consider two hypothetical accounts with a $10,000 balance:
| Account feature | Account A | Account B |
| Annual percentage yield | 3.00% | 4.00% |
| Starting balance | $10,000 | $10,000 |
| Approximate interest after one year | $300 | $400 |
| Ending balance | $10,300 | $10,400 |
Illustrative example only. These rates are hypothetical, not current market offers. Calculations assume no additional deposits or withdrawals and unchanged APYs.
In this example, Account B earns approximately $100 more over one year. Actual earnings depend on the account’s rate, compounding method, balance, and applicable terms.
Check whether each institution advertises an interest rate or an APY. These figures are related but not identical. APY incorporates compounding, making it more useful for comparing the annual earning potential of deposit accounts.
Also, remember that high-yield savings account rates are generally variable. A bank can change its APY, so today’s rate may not last throughout the year.
Look Beyond the Advertised Rate
An attractive APY does not always tell the whole story. Some accounts may offer promotional rates or impose conditions that affect which rate a customer receives.
Before opening an account, check the following:
- Promotional offers: Determine whether the advertised rate applies only for a limited period.
- Balance requirements: Find out whether a minimum balance is necessary to earn the stated APY.
- Eligibility conditions: Check whether the offer requires a particular account relationship or other qualifying activity.
- Rate changes: Review how the institution communicates changes to its savings rate.
Compare the terms that apply to your expected balance. A high advertised APY may be less useful if you cannot meet the requirements attached to it.
Do not assume that a rate will remain competitive indefinitely. Rechecking your account’s APY periodically can help you understand how it compares with other available options.
Compare Monthly Fees and Minimum Balances
Account fees can reduce the interest you earn. Some savings accounts charge monthly maintenance fees, while others have no monthly fee.
The Consumer Financial Protection Bureau explains that banks and credit unions may waive maintenance fees when customers meet certain conditions, such as maintaining a minimum balance or receiving qualifying direct deposits. The institution must disclose applicable fees and the conditions for avoiding them. (CFPB guidance)
Review these details before comparing accounts:
- Monthly maintenance fee: Determine whether the account charges a recurring fee.
- Minimum opening deposit: Check how much money you need to open the account.
- Minimum balance: Find out whether a particular balance is required to avoid fees or qualify for a stated APY.
- Fee waiver conditions: Check whether you must maintain a balance or complete other qualifying activities.
- Other charges: Review potential fees for wire transfers, expedited services, or other transactions.
A minimum opening deposit is not necessarily the same as a minimum balance requirement. An account might allow you to open it with a small deposit but require a higher balance to avoid fees.
Consider a hypothetical account that earns $100 in interest over a year but charges $5 per month in maintenance fees. The $60 in annual fees would reduce the interest benefit to $40, before considering other charges or taxes.
This is why comparing the net benefit after fees can be more informative than comparing APYs alone.
Verify FDIC or NCUA Deposit Protection
Deposit insurance is another important factor when comparing high-yield savings accounts.
For eligible deposits at an FDIC-insured bank, the Federal Deposit Insurance Corporation (FDIC) provides standard coverage of up to $250,000 per depositor, per insured bank, for each ownership category. The applicable limit includes eligible deposit accounts held in the same ownership category at that bank. (FDIC deposit insurance guidance)
Federally insured credit unions provide comparable protection through the National Credit Union Administration (NCUA). Standard coverage generally reaches $250,000 for an individual account owner, subject to applicable ownership rules and requirements. (NCUA share insurance guidance)
Before opening an account:
- Confirm that the institution is FDIC-insured or federally insured by the NCUA, as applicable.
- Verify that the specific product is an eligible deposit account.
- Consider other deposits you already hold at the same institution.
- Review the ownership category and applicable coverage limits if your combined balances are substantial.
Not every financial product offered by a bank or credit union qualifies for deposit insurance. Mutual funds, stocks, bonds, and certain other investment products are not covered by FDIC deposit insurance simply because a bank offers them.
Deposit insurance protects eligible deposits against the failure of an insured institution. It does not protect against inflation, every type of fraud, or a reduction in the interest rate paid by an account.
Check How Easily You Can Access Your Money
A high-yield savings account may be intended for emergency savings, future expenses, or money you want to keep separate from everyday spending. Access matters, particularly when you need funds quickly.
Compare the account’s transfer and withdrawal options.
Online transfers: Can you move money easily between your savings account and an external checking account? Check processing times and whether transfer limits apply.
ATM access: Some accounts offer ATM cards, while others require you to transfer money to another account before making cash withdrawals.
Branch access: Online banks may not have local branches. Consider whether in-person assistance or cash deposits are important to you.
Transfer fees: Check whether wire transfers, expedited transfers, or other services carry additional charges.
Withdrawal rules: Review the account agreement for applicable transaction restrictions, fees, or processing conditions.
Federal rules governing certain savings-account withdrawal limits have changed over time, and individual institutions may have their own account terms. Do not assume that every account has the same restrictions.
If you expect to use your savings for emergencies, consider how quickly you could access the money and whether the process would be convenient.
Evaluate Digital Banking and Customer Support
Many high-yield savings accounts are offered by online banks. Some traditional banks and credit unions also provide high-yield options.
Digital banking can be convenient, but account features and service quality vary.
Compare these features:
- Mobile banking: Check whether the app supports transfers, balance checks, and account management.
- Security alerts: Look for notifications about logins, transactions, and changes to account information.
- Customer service: Review available contact methods and support hours.
- Account recovery: Understand how to regain access if you lose your phone or forget your login details.
- Statements and records: Check whether statements and transaction histories are easy to access.
An online account may suit someone who prefers managing finances from home. Another customer may value branch access or the ability to speak with a representative in person.
Neither option is automatically better for everyone. The relevant question is whether the available services meet your needs.
Read the Fine Print Before Opening an Account
Once you have identified a few accounts worth considering, review their official disclosures and account agreements.
Use this checklist to keep the comparison consistent:
- Current APY and variable-rate terms
- Promotional rate conditions, if any
- Monthly maintenance fees
- Minimum opening deposit
- Minimum balance requirements
- Fees for transfers and other services
- FDIC or NCUA insurance status
- Withdrawal and transfer conditions
- Account eligibility requirements
- Mobile banking and customer support options
- Joint ownership and beneficiary options, if available
Read the terms directly from the financial institution rather than relying only on advertisements or third-party comparison pages. Account details can change, and published comparisons may not reflect the latest conditions.
Compare Accounts Side by Side
A simple table can help you identify differences without losing track of important details.
The following example uses hypothetical features. It does not describe actual bank products.
| Feature | Account A | Account B | What to consider |
| APY | 3.50% | 3.75% | Is the rate variable or promotional? |
| Monthly fee | $0 | $5 | Can the fee be avoided? |
| Opening deposit | $25 | $100 | Does the initial requirement fit your budget? |
| Minimum balance | None | $500 to avoid a fee | Can you maintain the required balance? |
| Deposit insurance | To be verified | To be verified | Is the institution federally insured? |
| Transfers | Online transfers | Online and wire transfers | Which methods are available, and what do they cost? |
| Customer support | Online and phone | Online, phone, and branch | Which service options matter to you? |
Account A has a lower hypothetical APY, but no monthly fee or ongoing balance requirement. Account B offers a higher APY but charges a fee and requires a minimum balance to avoid it.
The table illustrates why a single feature cannot determine the overall value of an account. The impact of each condition depends on the balance maintained and how the account is used.
For a fair comparison, use the same balance, time period, and assumptions for each account.
Common Mistakes to Avoid
Choosing an account based only on APY. A higher rate may not outweigh fees or requirements that apply to your circumstances.
Ignoring minimum balance rules. An account may require you to maintain a certain balance to avoid fees or qualify for a particular rate.
Assuming rates never change. Variable APYs can rise or fall, affecting future interest earnings.
Overlooking access limitations. Transfer delays or limited cash access can be inconvenient when money is needed quickly.
Confusing deposit insurance with investment protection. FDIC and NCUA insurance applies to eligible deposits under specific rules, not every product sold by a financial institution.
Relying on outdated comparisons. Rates, fees, and account conditions may change after a review is published.
Taking time to verify these details can help you compare accounts more accurately.
Bottom Line
Comparing high-yield savings accounts involves more than finding the highest advertised APY. Fees, minimum balance requirements, deposit insurance, transfer options, and customer service all deserve attention.
Start by comparing the APY and calculating how fees might affect your interest earnings. Then verify deposit protection and review the account’s access options and official terms.
A side-by-side comparison can make the differences easier to understand. Before opening an account, confirm that the published rate and conditions still apply.
Sources
- Consumer Financial Protection Bureau — Monthly maintenance fees
- Federal Deposit Insurance Corporation — Understanding Deposit Insurance
- National Credit Union Administration — Share Insurance Coverage
This article provides general information and is not individualized financial, tax, legal, or insurance advice.
- Start by Comparing APY
- Look Beyond the Advertised Rate
- Compare Monthly Fees and Minimum Balances
- Verify FDIC or NCUA Deposit Protection
- Check How Easily You Can Access Your Money
- Evaluate Digital Banking and Customer Support
- Read the Fine Print Before Opening an Account
- Compare Accounts Side by Side
- Common Mistakes to Avoid
- Bottom Line
- Sources
