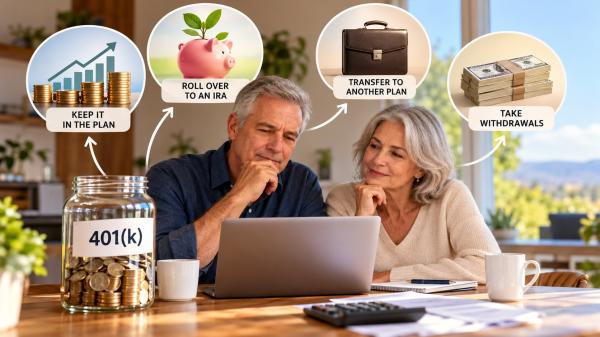
Retirement does not automatically require you to withdraw all the money in your 401(k). In many cases, you can leave the funds in your former employer’s plan, transfer them to an individual retirement account (IRA), or withdraw money over time. The available options depend on your plan’s rules and your financial circumstances.
Each choice can affect your taxes, investment options, and access to your savings. Understanding these differences can help you evaluate your next steps. You should also know when required minimum distributions begin and how different withdrawal methods may affect your retirement income.
Do You Have to Withdraw Your 401(k) When You Retire?
No. Retiring does not automatically require you to cash out your entire 401(k) balance.
Many employer-sponsored retirement plans allow former employees to keep their money in the plan. However, some plans impose balance requirements or other restrictions. Your plan documents explain the options available to you.
You may also be able to transfer the funds into an IRA or another eligible employer-sponsored retirement plan. Alternatively, you can take distributions according to the plan’s rules.
Your age matters, too. Federal tax law establishes required minimum distribution rules for many retirement accounts. These rules may eventually require you to withdraw a certain amount, even if you do not need the money for living expenses.
The important distinction is that retirement, account access, and mandatory withdrawals are three separate issues.
What Are Your Options for Your 401(k) After Retirement?
Your former employer’s plan may offer several ways to manage your retirement savings. Each option has different rules, costs, and practical considerations.
1. Leave the Money in Your Former Employer’s Plan
You may be able to keep your 401(k) with your former employer after retiring.
This option lets you maintain your existing retirement account without immediately transferring the money. Your balance can remain invested according to the plan’s available investment choices.
However, you should review the plan’s fees, investment options, withdrawal procedures, and minimum balance requirements. Some plans may limit how frequently you can withdraw money or require specific distribution arrangements.
Leaving your money in the plan does not guarantee investment growth. Your balance can rise or fall depending on the investments you hold.
2. Roll Over Your 401(k) Into an IRA
An individual retirement account, or IRA, is another type of retirement account. You may be eligible to transfer your 401(k) savings into one after leaving your employer.
An IRA may offer a different range of investment choices and fee structures. However, the available investments and costs depend on the account provider.
A direct rollover transfers eligible funds from your employer’s plan to the receiving retirement account. This generally avoids current federal income tax on the transferred amount when the rollover follows the applicable rules.
Be careful when handling a distribution yourself. Eligible distributions paid directly to you may be subject to mandatory federal income tax withholding. You generally have 60 days to complete an eligible rollover after receiving the funds.
A rollover does not automatically reduce fees or improve investment performance. Compare the terms of both accounts before making a decision.
3. Transfer the Money to Another Employer’s Plan
If you continue working after retiring from your primary career, you might have access to another employer’s retirement plan.
Some plans accept eligible rollovers from previous employers. Others do not.
Check the receiving plan’s rules before initiating a transfer. Compare its investment options, fees, withdrawal restrictions, and administrative procedures with those of your existing account.
This option may help consolidate retirement savings, but eligibility depends on the receiving plan.
4. Withdraw Some or All of the Money
You may be able to take money from your 401(k) as a lump sum, in installments, or through other distribution arrangements permitted by the plan.
A lump-sum withdrawal gives you access to a larger amount at once. However, a taxable distribution from a traditional 401(k) generally increases your taxable income for that year.
Smaller withdrawals may spread taxable income across multiple years, depending on your circumstances and the amount withdrawn. They can also reduce the balance available for future retirement expenses.
Before withdrawing money, review the plan’s distribution rules and consider how the withdrawal may affect your overall income and tax situation.
What Happens to Your 401(k) Taxes When You Retire?
Taxes depend partly on whether your savings are in a traditional 401(k) or a designated Roth 401(k).
Traditional 401(k)
Contributions are generally made before federal income taxes. Withdrawals are generally taxable as ordinary income, except for any portion that receives different treatment under applicable tax rules.
Roth 401(k)
Contributions are made with after-tax money. Qualified distributions are generally tax-free, including investment earnings, when the applicable requirements are met.
The distinction matters because the same withdrawal amount can have different tax consequences depending on the account type.
For example, a retiree taking money from a traditional 401(k) may need to account for the distribution when calculating federal taxable income. A qualified Roth 401(k) distribution generally does not create the same federal income tax liability.
A direct rollover between eligible accounts can generally preserve tax-deferred treatment when the transaction follows IRS rules. However, moving pretax money into a Roth account generally creates a taxable conversion.
Your state may also impose income taxes. The final tax impact depends on the type of account, the transaction, and your individual circumstances. The IRS provides further guidance in its 401(k) distribution rules.
When Do You Have to Start Taking 401(k) Withdrawals?
Federal law requires many retirement account owners to begin taking required minimum distributions, commonly called RMDs, at a specified age.
For most traditional 401(k) participants, the general starting age is 73. The deadline for the first distribution is generally April 1 of the year after the year the participant reaches the applicable starting age or, when the rules allow, retires later.
An important exception may apply if you are still working for the employer sponsoring your plan. An eligible participant may be able to delay RMDs from that employer’s plan until retirement. This exception generally does not apply to a 5% owner of the business. The plan’s terms and applicable IRS rules determine whether you qualify.
Designated Roth 401(k) accounts also have different rules. Under current federal law, the original account owner is not required to take lifetime RMDs from a designated Roth account. Beneficiary distribution rules are different.
Missing an RMD deadline can lead to an additional tax unless an applicable correction or waiver applies. You should verify your required beginning date and calculate the correct distribution amount with reliable, current information.
You can find more details in the IRS’s Required Minimum Distributions FAQs.
What Happens If You Cash Out Your 401(k)?
Cashing out means withdrawing money from your retirement account rather than keeping it in a retirement plan or completing an eligible rollover.
A full cash-out can have several consequences:
- Income taxes: Traditional 401(k) withdrawals are generally taxable in the year you receive them.
- Possible additional tax: Certain early distributions may incur an additional 10% federal tax. Exceptions can apply, including specific rules for distributions after leaving an employer in or after the year you turn 55. The applicable requirements matter.
- Less money invested: Once you withdraw the funds, that money is no longer invested inside the retirement account.
- Reduced future flexibility: Spending a large portion of your savings at once may leave less available for later retirement expenses.
For example, imagine someone has $100,000 in a traditional 401(k) and withdraws the entire balance. The amount received after withholding and the eventual tax liability may be substantially different from $100,000.
The actual outcome depends on the person’s taxable income, applicable tax rules, and any additional taxes or exceptions. This example is illustrative, not a prediction of anyone’s tax bill.
Cashing out is not the same as rolling over an account. An eligible rollover can preserve tax-deferred treatment, while a taxable withdrawal can create an immediate tax obligation.
What Should You Check Before Making a Decision?
Before deciding what to do with your 401(k), review the following details.
Retirement account checklist
0 of 7
Read your former employer’s 401(k) plan documents.
Compare account fees and available investments.
Check the rules for withdrawals and installment payments.
Confirm whether a direct rollover to an IRA or another plan is available.
Understand the tax treatment of traditional and Roth funds.
Determine whether you must take required minimum distributions.
Consider how withdrawals fit into your retirement income needs.
Your plan administrator can explain the distribution options available under your specific plan. The IRS provides guidance on federal tax rules, while a qualified tax professional can help evaluate how those rules apply to your circumstances.
Bottom Line
Your 401(k) does not automatically have to be paid out when you retire. Depending on your plan, you may be able to leave the money invested, roll it into an IRA, transfer it to another eligible employer plan, or withdraw funds over time.
The main considerations are taxes, fees, investment choices, access to your money, and required minimum distributions. A full cash-out is only one possible option, and it can create tax consequences that deserve careful consideration.
Review your plan documents and verify current IRS rules before making a decision. Understanding the available choices can help you evaluate how your retirement savings fit into your broader financial plans.
Sources
- Internal Revenue Service — 401(k) Resource Guide: General Distribution Rules
- Internal Revenue Service — Rollovers of Retirement Plan and IRA Distributions
- Internal Revenue Service — Required Minimum Distributions FAQs
- U.S. Department of Labor — Retiring from a Job
- U.S. Department of Labor — What You Should Know About Your Retirement Plan
- Do You Have to Withdraw Your 401(k) When You Retire?
- What Are Your Options for Your 401(k) After Retirement?
- 1. Leave the Money in Your Former Employer’s Plan
- 2. Roll Over Your 401(k) Into an IRA
- 3. Transfer the Money to Another Employer’s Plan
- 4. Withdraw Some or All of the Money
- What Happens to Your 401(k) Taxes When You Retire?
- Traditional 401(k)
- Roth 401(k)
- When Do You Have to Start Taking 401(k) Withdrawals?
- What Happens If You Cash Out Your 401(k)?
- What Should You Check Before Making a Decision?
- Retirement account checklist
- 0 of 7
- Bottom Line
- Sources
