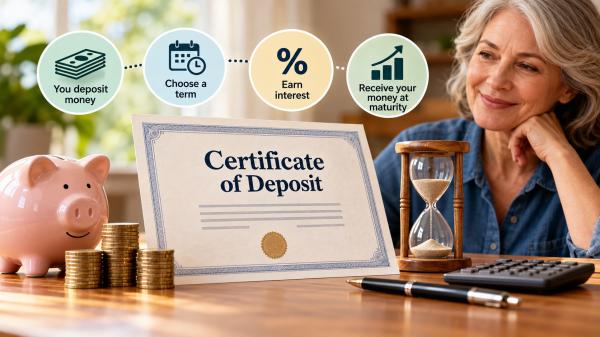
A certificate of deposit (CD) is a type of savings account that pays interest in exchange for keeping your money deposited for a specified period. Banks and credit unions offer CDs with different terms, interest rates, and withdrawal rules.
Unlike a regular savings account, a traditional CD generally limits access to your money until the account reaches maturity. Withdrawing funds early may trigger a penalty.
Understanding how CDs work can help you compare savings options, evaluate potential earnings, and decide how much flexibility you may need. The key factors include the annual percentage yield (APY), term length, early withdrawal penalties, and deposit insurance.
What Is a Certificate of Deposit?
A certificate of deposit is a deposit account designed to hold money for a predetermined period. In exchange, the financial institution pays interest according to the account’s terms.
CD terms may range from a few months to several years. Common options include six-month, one-year, three-year, and five-year CDs, although available terms vary by institution.
When you open a traditional CD, you typically agree to leave your initial deposit in the account until a specified maturity date. The institution agrees to pay interest under the terms disclosed when you open the account.
For example, you might deposit $5,000 into a one-year CD. The account earns interest during that year, and you receive the principal and applicable earnings according to its terms.
A CD is different from a stock, bond, or mutual fund. An eligible bank CD is a deposit account, and qualifying deposits may receive federal deposit insurance. However, not every product marketed as a CD has identical features or protections.
The Consumer Financial Protection Bureau (CFPB) explains the basic structure and withdrawal restrictions of CDs in its official guide to certificates of deposit.
How Does a CD Work?
Opening and maintaining a traditional CD generally involves five steps.
1. Choose a CD and deposit money. Compare financial institutions, minimum deposit requirements, interest rates, and available terms. Some CDs require a minimum opening deposit, while others do not.
2. Agree to a term. The term determines how long the money is scheduled to remain deposited. A longer term may offer different interest terms than a shorter one, but it does not always offer a higher rate.
3. Earn interest. The financial institution calculates interest according to the account agreement. The rate may be fixed or variable, depending on the product.
4. Reach the maturity date. Maturity marks the end of the CD’s scheduled term. At that point, the institution generally makes the principal and applicable interest available according to the account’s terms.
5. Decide what happens next. You may be able to withdraw the funds, transfer them elsewhere, or renew the CD. Some accounts renew automatically unless you act within a specified period.
Before opening a CD, read the account disclosures carefully. They explain when interest is paid, whether withdrawals are permitted, and what happens at maturity.
How Do CD Interest Rates and APY Work?
Two important terms help explain how much a CD may earn: the interest rate and the annual percentage yield.
- Interest rate: The rate used to calculate interest on the deposit, subject to the account’s terms.
- Annual percentage yield (APY): A standardized measure of annual earnings that accounts for compounding, assuming the stated conditions apply.
APY can make it easier to compare CDs with different interest-payment and compounding arrangements. However, the term length and withdrawal conditions also matter.
A hypothetical CD earnings example
Suppose you deposit $5,000 into a one-year CD with a fixed APY of 4%.
If the funds remain deposited for the full year and the stated APY applies, the account would earn approximately $200 in interest.
| Item | Hypothetical amount |
| Initial deposit | $5,000 |
| APY | 4% |
| Term | One year |
| Interest earned | $200 |
| Total at maturity | $5,200 |
This example assumes no fees, early withdrawal, or other adjustments. The 4% APY is hypothetical, not a statement of a current market offer.
Actual earnings depend on the CD’s terms, the amount deposited, and the applicable rate. Interest payments may also follow different schedules.
CD rates change as financial institutions adjust their offerings. Compare current APYs and verify the terms directly with each institution before making a decision.
What Happens When a CD Matures?
A CD matures when its agreed term ends. The financial institution then makes the principal and applicable interest available according to the account agreement.
Depending on the CD, you may be able to:
- Withdraw the principal and interest.
- Transfer the funds to another account.
- Use the proceeds to open a new CD.
- Allow the CD to renew automatically.
Some banks and credit unions automatically renew CDs if you do not provide instructions before a specified deadline. The renewal CD may have a different interest rate or term.
The CFPB explains that institutions must provide written notice before maturity when automatic renewal applies. Review the notice and compare available rates before the renewal deadline.
Learn more in the CFPB’s guide to CD rollovers and renewals.
What Happens If You Withdraw Money Early?
Traditional CDs generally restrict withdrawals before maturity. If you need the money early, the institution may charge an early withdrawal penalty.
The penalty depends on the account agreement. Some institutions calculate it using a specified number of days or months of interest. Other terms may apply.
Consider a hypothetical example: You open a CD expecting to leave the money untouched for one year. Six months later, an unexpected expense requires you to access those funds.
An early withdrawal penalty could reduce your interest earnings. Depending on the terms and the interest already earned, the penalty could also reduce the principal you receive.
Before opening a CD, check:
- Whether early withdrawal is permitted.
- How the penalty is calculated.
- Whether the penalty can exceed the interest earned.
- Whether any exceptions apply.
Brokered CDs can work differently. They may be sold in a secondary market rather than withdrawn like a traditional bank CD. If market conditions are unfavorable, selling a brokered CD before maturity could result in a loss of principal.
The Securities and Exchange Commission (SEC) provides additional information about these risks in its brokered CD investor bulletin.
Are CDs Safe?
CDs can be a relatively conservative way to hold savings, but the type of CD and its protections matter.
FDIC insurance for bank CDs
Eligible deposits at FDIC-insured banks are generally protected up to $250,000 per depositor, per insured bank, per ownership category.
The limit applies to the combined eligible deposits within the same ownership category at that bank. It does not automatically provide a separate $250,000 limit for every CD.
For example, a person’s qualifying savings account and CD at the same bank may count toward the same insurance limit if both fall within the same ownership category.
NCUA insurance for credit union CDs
Federally insured credit unions provide comparable protection through the National Credit Union Administration (NCUA). Eligible share certificates and other qualifying deposits generally receive coverage subject to applicable limits and ownership rules.
Check that the institution is federally insured and confirm how your accounts are classified.
Other risks to consider
Even an insured CD has limitations:
- Inflation risk: Prices may rise faster than your earnings, reducing your purchasing power.
- Liquidity risk: Your money may be difficult or costly to access before maturity.
- Reinvestment risk: Rates available when your CD matures may be lower than your original rate.
- Product-specific risk: Brokered CDs and CDs with special features may involve additional considerations.
Deposit insurance does not eliminate every financial risk. It protects eligible deposits against the failure of the insured institution, subject to applicable rules and limits.
You can verify coverage through the FDIC or the NCUA.
What Are the Advantages and Disadvantages of CDs?
A CD may appeal to savers who value predictable earnings, but its restrictions may not suit every situation.
| Potential advantages | Potential disadvantages |
| Fixed-rate CDs offer a predictable interest rate for the term. | Early withdrawals may trigger penalties. |
| Terms can help establish a savings timeline. | Money may be less accessible than savings account funds. |
| Eligible deposits may receive federal insurance. | Inflation can reduce purchasing power. |
| Interest earnings can be estimated in advance for fixed-rate CDs. | Rates on new CDs may be more attractive after you open yours. |
| Different terms offer flexibility when planning savings. | Automatic renewal may lock funds into a new term if you miss the deadline. |
The balance between access and predictability is central to understanding CDs. A fixed rate can make earnings easier to estimate, but it also means you may not benefit from higher rates offered later.
CD vs. Savings Account: What’s the Difference?
Both CDs and savings accounts can help you hold money and earn interest. Their main difference is access to the funds and the terms governing interest.
| Feature | Traditional CD | Savings account |
| Access to money | Generally restricted until maturity | Generally easier to access |
| Interest rate | Often fixed for the term | Often variable |
| Term | Set in advance | Usually no fixed maturity |
| Early withdrawal | May trigger a penalty | Generally no CD-style maturity penalty |
| Deposit insurance | Available for eligible deposits | Available for eligible deposits |
Actual account features vary by institution. Some CDs have variable rates or special withdrawal provisions, while savings accounts may have their own fees or account conditions.
A CD may be worth comparing when you can leave money untouched for a defined period. A savings account may offer more flexibility when you need regular access to your funds.
For a broader comparison, see High-Yield Savings vs. Regular Savings: What’s the Difference?
What Should You Compare Before Opening a CD?
Before choosing a CD, review these details in the account agreement:
1. APY: Compare annual yields rather than looking only at the stated interest rate.
2. Term length: Consider when you expect to need the money.
3. Minimum deposit: Confirm the amount required to open the account.
4. Early withdrawal penalty: Understand the potential cost of accessing funds early.
5. Maturity instructions: Check whether the CD renews automatically and how much time you have to act.
6. Deposit insurance: Verify the institution and calculate how the CD fits within your existing coverage.
7. Special features: Review variable rates, call provisions, fees, and any other conditions that could affect earnings or access.
CD interest is generally taxable under U.S. federal income tax rules, although the timing of reporting can depend on the account’s structure. The IRS explains the rules in Publication 550.
Frequently Asked Questions About CDs
Can you lose money in a CD?
An eligible CD held at an insured institution is protected against institutional failure within applicable insurance limits. However, early withdrawal penalties, fees, inflation, and certain brokered CD transactions can affect your financial outcome.
Are CD earnings taxable?
CD interest is generally subject to federal income tax. Reporting requirements and timing can vary by product and circumstances. Consult the IRS or a qualified tax professional if you have questions about your situation.
Can you add money to a CD after opening it?
Traditional CDs commonly require a single initial deposit. Some products may allow additional deposits, but this depends on the account’s terms. Confirm the rules before opening an account.
What happens if you do nothing when a CD matures?
The CD may renew automatically, depending on its terms. The renewal may have a different interest rate or maturity date. Check the maturity notice and account agreement for the deadline to withdraw or change your instructions.
Is a CD different from a money market account?
Yes. A traditional CD generally has a fixed term and may impose an early withdrawal penalty. A money market deposit account generally offers easier access to funds, subject to its account rules. Both may qualify for federal deposit insurance when offered by an eligible insured institution.
Bottom Line
A certificate of deposit allows you to deposit money for a specified period and earn interest under agreed terms. Fixed-rate CDs can make earnings more predictable, but early withdrawal restrictions may limit access to your money.
Before opening a CD, compare APY, term length, penalties, maturity instructions, and deposit insurance. Consider when you may need the funds and verify the current terms directly with the financial institution.
A CD is one savings option among several. Understanding its conditions can help you compare it with savings accounts and other ways to hold cash without assuming that one option is right for everyone.
Sources
- Consumer Financial Protection Bureau — What Is a Certificate of Deposit?
- Consumer Financial Protection Bureau — CD Rollovers and Renewals
- FDIC — Federal Deposit Insurance
- NCUA — Share Insurance Coverage
- Investor.gov — Certificates of Deposit
- SEC / Investor.gov — Brokered CDs
- Internal Revenue Service — Publication 550
- What Is a Certificate of Deposit?
- How Does a CD Work?
- How Do CD Interest Rates and APY Work?
- A hypothetical CD earnings example
- What Happens When a CD Matures?
- What Happens If You Withdraw Money Early?
- Are CDs Safe?
- FDIC insurance for bank CDs
- NCUA insurance for credit union CDs
- Other risks to consider
- What Are the Advantages and Disadvantages of CDs?
- CD vs. Savings Account: What's the Difference?
- What Should You Compare Before Opening a CD?
- Frequently Asked Questions About CDs
- Can you lose money in a CD?
- Are CD earnings taxable?
- Can you add money to a CD after opening it?
- What happens if you do nothing when a CD matures?
- Is a CD different from a money market account?
- Bottom Line
- Sources
