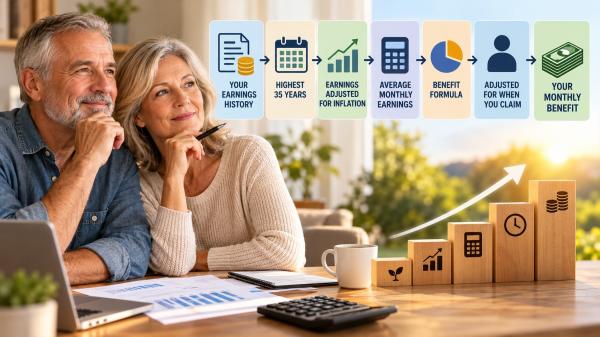
Social Security retirement benefits are based primarily on your earnings history and the age at which you start receiving benefits. The calculation is more involved than simply taking a percentage of your last salary.
The Social Security Administration generally looks at your highest 35 years of indexed earnings, calculates your Average Indexed Monthly Earnings (AIME), and then applies a formula to determine your Primary Insurance Amount (PIA). Your actual monthly benefit can then be higher or lower depending on when you claim.
Here is how the process works.
Social Security Starts With Your Earnings Record
Your Social Security retirement benefit is based on earnings from work covered by Social Security.
There is also a limit on how much earnings count for Social Security purposes in any given year. In 2026, the maximum amount of earnings subject to Social Security tax is $184,500. Earnings above that amount are not used as additional earnings for the benefit calculation for that year.
Your earnings record is important because Social Security does not calculate your retirement benefit from your final salary alone. It looks at your covered earnings over your working years.
Your Highest 35 Years Matter
For most retirement benefit calculations, Social Security uses up to 35 years of earnings.
The agency selects the years with the highest indexed earnings rather than simply choosing the years in which you earned the most dollars in nominal terms. Earlier earnings are adjusted to account for changes in average wages over time.
If you have fewer than 35 years of covered earnings, years without earnings can be included in the calculation. Those years effectively contribute zero earnings, which can lower your average.
This is one reason that working additional years can sometimes change a future Social Security benefit: a new year of earnings may replace a lower-earning year in the calculation.
Earlier Earnings Are Adjusted
A dollar earned decades ago is not treated exactly the same way as a dollar earned more recently.
For earnings before a worker reaches age 62, Social Security generally applies wage indexing to earlier earnings. The purpose is to adjust historical earnings so they can be considered in relation to changes in average wages.
For someone becoming eligible in 2026, for example, earnings from years before 2024 are indexed using the national average wage index. Earnings from 2024 and later are not wage-indexed in that particular calculation.
This adjustment is an important reason why trying to calculate a benefit by simply adding up old paychecks will not produce the official Social Security benefit amount.
What Is Average Indexed Monthly Earnings?
After the applicable earnings have been indexed, Social Security selects the highest years needed for the calculation.
For a standard retirement calculation using 35 years, those earnings represent 420 months. The indexed earnings are added together and divided by 420 to produce the worker’s Average Indexed Monthly Earnings, or AIME.
The AIME is then used in the next stage of the calculation.
Think of it this way:
Earnings history → highest indexed earnings → AIME → benefit formula
The AIME is not your final Social Security check. It is one of the numbers used to determine the benefit.
What Is the Primary Insurance Amount?
The next step is determining the Primary Insurance Amount, or PIA.
The PIA is the basic retirement benefit associated with a worker’s earnings record when claimed at full retirement age, before adjustments for claiming earlier or later.
The formula uses different percentages for different portions of the AIME. The dollar thresholds used in the formula are called bend points, and they change over time.
For workers becoming eligible in 2026, the formula is:
- 90% of the first $1,286 of AIME
- 32% of AIME over $1,286 through $7,749
- 15% of AIME above $7,749
The structure is progressive. That means the same percentage is not applied to every dollar of AIME.
For example, if a hypothetical worker has an AIME of $5,000 and first becomes eligible in 2026, the calculation would use 90% for the first $1,286 and 32% for the portion between $1,286 and $5,000. It would not apply 32% to the entire $5,000.
The actual calculation can also involve additional adjustments and rounding rules.
Why Does the Year You Turn 62 Matter?
The Social Security benefit formula is tied to the year a worker becomes eligible, which for retirement purposes generally means the year the person reaches age 62.
That means the bend points used in the PIA formula are not the same for every generation. For example, the 2026 bend points are $1,286 and $7,749, while the figures were different for workers becoming eligible in earlier years.
This is why an old Social Security calculation example found online may not accurately describe the formula for someone reaching age 62 in a different year.
Your Claiming Age Can Change the Monthly Benefit
Calculating the PIA is not necessarily the final step.
The age at which you begin receiving retirement benefits can increase or decrease your monthly payment.
You can generally begin Social Security retirement benefits as early as age 62, but starting before full retirement age results in a reduced monthly benefit.
For people born in 1960 or later, full retirement age is 67. If a person in that group starts benefits at 62, the worker’s retirement benefit can be reduced to 70% of the full retirement benefit amount.
Waiting beyond full retirement age can have the opposite effect. Delayed retirement credits can increase the monthly benefit for each month of delay up to age 70. For people born in 1960 or later, starting at age 70 results in 124% of the full retirement benefit amount. There is no additional delayed-retirement increase after age 70.
The claiming-age adjustment is therefore separate from the underlying calculation based on your earnings history.
What Happens If You Don’t Have 35 Years of Earnings?
Suppose someone has only 28 years of covered earnings.
Social Security still uses the applicable computation period, but years without earnings can result in zeroes being included when calculating the average. That can reduce the AIME compared with a worker who has 35 years of qualifying earnings.
On the other hand, an additional year of work may help if the new earnings are higher than one of the lower-earning years already included in the calculation.
That does not mean every additional year of work will automatically increase a person’s benefit. It depends on the earnings record and the years being replaced.
A Simple Hypothetical Example
Consider a hypothetical worker who has 35 years of earnings after the applicable indexing process.
Suppose the worker’s resulting AIME is $5,000 and the worker becomes eligible under the 2026 formula.
The PIA calculation would begin with:
- 90% of the first $1,286
- 32% of the amount from $1,286 through $5,000
- Nothing from the third bracket because the AIME does not exceed $7,749
The resulting PIA would then represent the worker’s basic benefit amount before any applicable early- or delayed-retirement adjustment.
This example is only an illustration. A person’s actual Social Security calculation depends on their individual earnings record, eligibility year, claiming age and other applicable rules.
Does Working Longer Always Increase Social Security?
Not necessarily.
Social Security uses the highest applicable years in the earnings calculation. If a new year of earnings is higher than one of the years already being used, it can replace that lower year and potentially increase the benefit.
But if the additional year does not improve the relevant earnings record, the effect on the calculation may be limited.
Working longer can also affect the timing of when benefits are claimed, which is a separate issue from the earnings calculation itself.
How Can You See Your Estimated Social Security Benefit?
The easiest way to get an estimate based on your own earnings history is through your personal Social Security account.
An estimate based on your actual earnings record is more useful than applying a generic formula to an assumed salary because Social Security calculations depend on the details of your work history.
The agency also provides tools and information explaining how retirement benefits are calculated and how different claiming ages can affect the monthly amount.
Common Questions About Social Security Calculations
Is Social Security based on your last 10 years of work?
No. The standard retirement benefit calculation generally uses up to your highest 35 years of indexed earnings, not simply your last 10 years.
What if I worked fewer than 35 years?
Years without earnings can be included in the calculation, which can reduce the average used to determine your benefit.
Does my highest salary determine my Social Security benefit?
No. Your benefit is based on your broader earnings record rather than just your highest salary or final salary.
Can I start Social Security at 62?
Generally, yes. Retirement benefits can begin as early as age 62, but claiming before full retirement age reduces the monthly benefit.
Does waiting until 70 increase Social Security?
For eligible workers, delaying retirement benefits beyond full retirement age can increase the monthly benefit through delayed retirement credits. The increase stops at age 70.
Are Social Security benefit formulas the same every year?
No. The percentages in the basic PIA formula are established by law, but the dollar thresholds, known as bend points, change according to the applicable year.
Bottom Line
Social Security retirement benefits are calculated from your earnings history, not simply from your last paycheck.
The process generally involves selecting your highest applicable years of indexed earnings, calculating your Average Indexed Monthly Earnings (AIME), applying the Primary Insurance Amount (PIA) formula, and then adjusting the benefit based on when you claim.
For 2026, the PIA formula uses bend points of $1,286 and $7,749 for workers becoming eligible that year. But those numbers are not permanent and should not be applied to every worker regardless of age or eligibility year.
If you are planning for retirement, your own Social Security earnings record and official benefit estimate are the most useful starting points for understanding what you may receive.
This article provides general information and is not individualized financial, tax, legal or insurance advice.
Sources
- Social Security Administration, Social Security Retirement Benefit Calculation
- Social Security Administration, Social Security Benefit Amounts
- Social Security Administration, Primary Insurance Amount
- Social Security Administration, Benefit Formula Bend Points
- Social Security Administration, Retirement Age and Benefit Reduction
- Social Security Starts With Your Earnings Record
- Your Highest 35 Years Matter
- Earlier Earnings Are Adjusted
- What Is Average Indexed Monthly Earnings?
- What Is the Primary Insurance Amount?
- Why Does the Year You Turn 62 Matter?
- Your Claiming Age Can Change the Monthly Benefit
- What Happens If You Don't Have 35 Years of Earnings?
- A Simple Hypothetical Example
- Does Working Longer Always Increase Social Security?
- How Can You See Your Estimated Social Security Benefit?
- Common Questions About Social Security Calculations
- Is Social Security based on your last 10 years of work?
- What if I worked fewer than 35 years?
- Does my highest salary determine my Social Security benefit?
- Can I start Social Security at 62?
- Does waiting until 70 increase Social Security?
- Are Social Security benefit formulas the same every year?
- Bottom Line
- Sources
